White Label Cost Segregation Implementation Pitfalls for CPA Firms
Implementing a white label cost segregation program can dramatically expand a CPA firm's service offerings and improve client retention. However, the transition from a standard advisory practice to a specialized depreciation provider introduces complex operational risks. According to recent industry analyses, firms that fail to establish rigorous quality control protocols often face significant compliance challenges during IRS examinations. This guide outlines the critical implementation pitfalls that can undermine your white label strategy and how to avoid them. (About RentalWriteOff Cost Segregation)
Understanding White Label Cost Segregation
White label cost segregation allows CPA firms to offer specialized engineering-based depreciation studies under their own brand name. This model enables advisors to capture higher margins while maintaining the appearance of in-house expertise. The core value proposition lies in the ability to accelerate depreciation deductions for rental property owners, thereby reducing their current tax liability. (Cost Segregation Studies for)
Cost segregation is a tax strategy that identifies personal property components of real estate that can be depreciated over shorter recovery periods. Cost segregation is the process of reclassifying certain building components from real property to personal property for tax purposes. By separating elements like flooring, cabinetry, and landscaping from the building structure, investors can utilize accelerated depreciation methods such as bonus depreciation. (Cost Segregation Studies for)
For CPA firms, offering this service creates a sticky relationship with clients. When a firm helps a client save tens of thousands of dollars in taxes, the perceived value of the advisory relationship increases significantly. However, the operational complexity of delivering these studies requires careful management to avoid the pitfalls that plague many early adopters.
Vendor Selection and Quality Control Pitfalls
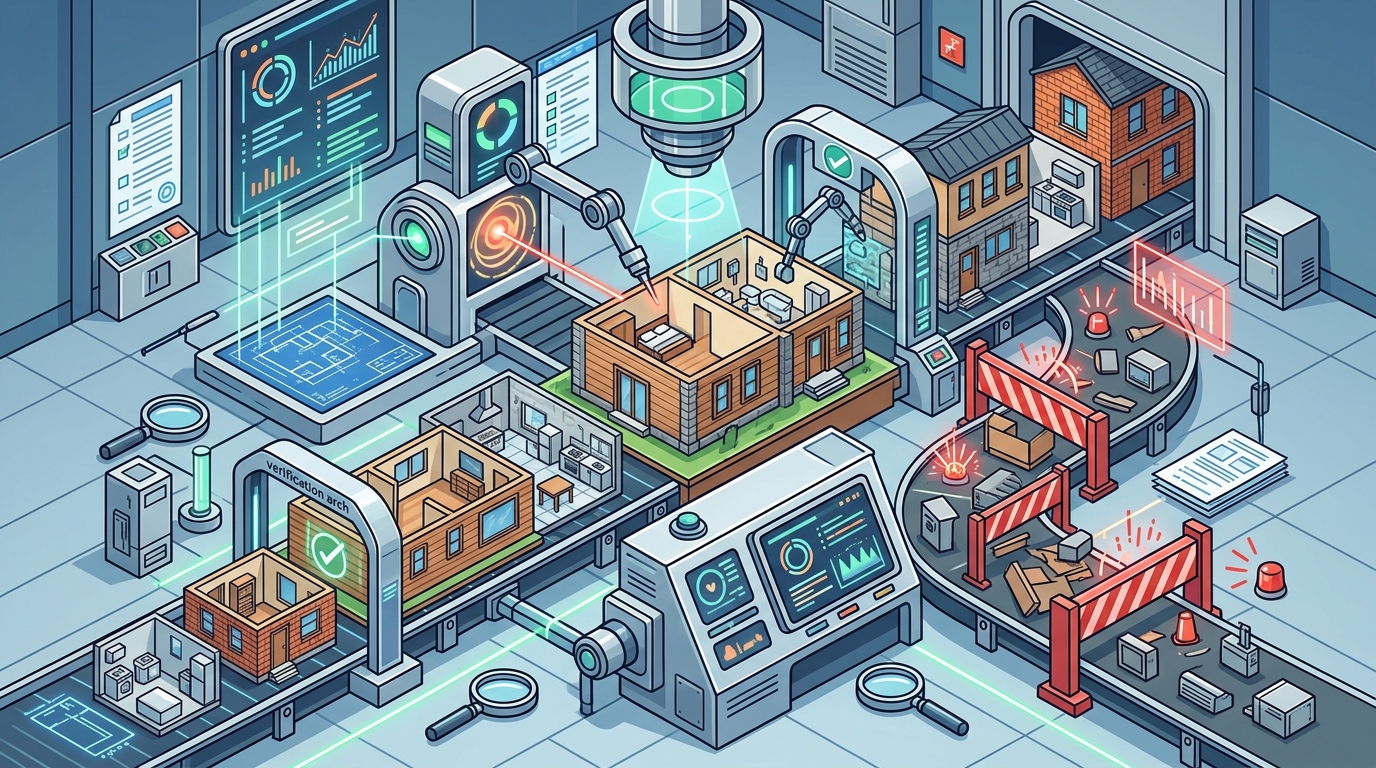
The most common implementation error is selecting a white label partner based solely on price. While low-cost providers may seem attractive initially, they often lack the engineering rigor required to withstand IRS scrutiny. A cost segregation study is not a generic estimate; it is a defensible engineering report that must align with specific IRS guidelines.
IRS Cost Segregation Audit Techniques Guide is the authoritative framework that dictates how studies must be structured to survive an audit. Vendors who do not adhere strictly to this guide produce reports that are vulnerable to disallowance. When a study is disallowed, the liability often falls back on the CPA firm that recommended the service, damaging their reputation and potentially leading to professional negligence claims.
To mitigate this risk, firms must evaluate potential partners on their quality assurance processes. Look for vendors who provide:
- Engineering-based methodologies rather than algorithmic averages.
- Expert review by qualified professionals before report delivery.
- Audit support services that include direct engagement with the IRS if necessary.
RentalWriteOff, for example, emphasizes an engineering-based methodology that is built on the official IRS Cost Segregation Audit Techniques Guide. Their approach ensures that each report includes a final quality check, which is critical for maintaining the integrity of the white label offering. Firms should prioritize partners who provide defensible pricing and classification for each asset class, ensuring that the 5, 7, and 15-year property buckets are accurately populated.
Technical and Workflow Integration Challenges
Integrating a white label cost segregation service into an existing CPA workflow is often underestimated. Many firms struggle with the data collection process, which requires detailed property information, construction costs, and sometimes on-site inspections. If the intake process is cumbersome, it creates bottlenecks that delay report delivery and frustrate clients.
Another significant pitfall is the lack of clear communication regarding the scope of work. Clients often confuse cost segregation with a general property appraisal. It is essential to educate clients on the difference between a market value appraisal and a tax basis allocation. A cost segregation study focuses exclusively on the tax code definitions of personal property versus real property, not on the fair market value of the asset.
Effective integration requires a seamless handoff between the CPA firm and the white label vendor. This includes establishing clear timelines for report delivery and defining the protocol for handling missing data. For instance, if a client cannot provide construction invoices, the vendor must have a robust methodology for estimating component values based on square footage and property type. Firms should verify that their partner can handle these scenarios without compromising the accuracy of the study.
Furthermore, the delivery format of the report must be compatible with the CPA firm's tax preparation software. A comprehensive final report should include all necessary schedules, statements, and methodologies required to be compliant with IRS standards. This includes an itemized CSV listing every classified asset with quantities and values, which facilitates easy import into tax software.
Compliance and Liability Risks
Liability management is a critical component of any white label arrangement. When a CPA firm recommends a cost segregation study, they are implicitly vouching for the quality and accuracy of the underlying data. If the study contains errors, the firm may be held liable for the resulting tax penalties and interest.
One major compliance risk is the misapplication of bonus depreciation rules. The tax code regarding bonus depreciation changes frequently. For example, property acquired after January 19, 2025, may qualify for 100% first-year bonus depreciation on reclassified assets. However, this rule has specific phase-out schedules and limitations that must be carefully applied. A white label partner who is not up-to-date with these changes can produce a study that is technically incorrect, leading to significant compliance issues.
Another risk is the failure to properly document the basis of the property. Cost segregation studies rely on the original cost basis of the building and its improvements. If the firm provides incorrect basis information to the vendor, the resulting allocations will be flawed. This is particularly challenging for legacy properties where construction records may be incomplete or lost.
To protect against these risks, CPA firms should include specific indemnification clauses in their agreements with white label partners. Additionally, firms should conduct their own internal review of the reports before presenting them to clients. This does not mean re-doing the engineering work, but rather verifying that the methodology is sound and the conclusions are defensible.
Pricing Strategy and Margin Analysis
Pricing a white label cost segregation service correctly is essential for profitability. Many firms make the mistake of marking up the vendor's price by a fixed percentage without considering the value delivered to the client. A well-executed cost segregation study can save a client hundreds of thousands of dollars in taxes, making the service fee seem negligible in comparison.
However, overpricing can also be a pitfall. If the fee is too high, clients may shop around for cheaper alternatives, potentially undermining the relationship. The key is to position the service as a high-value investment rather than a commodity. Firms should communicate the ROI clearly, highlighting the accelerated depreciation benefits and the long-term tax savings.
Consider the example of a $500,000 property. A standard depreciation schedule might allow for $18,000 in deductions per year over 27.5 years. With cost segregation, a significant portion of that basis can be reclassified into 5, 7, or 15-year buckets. In some cases, this can result in an additional $40,000 or more in cash back in the first year due to bonus depreciation. This dramatic shift in cash flow justifies a premium service fee.
Firms should also consider the operational costs of managing the white label relationship. This includes the time spent on client communication, data collection, and report review. If the vendor does not provide a user-friendly platform for tracking study status, the firm may incur hidden labor costs that erode margins. Choosing a partner with a streamlined digital interface, such as a free estimate calculator and automated status updates, can significantly reduce these overheads.
Key Takeaways
- Quality Over Price: Prioritize vendors with engineering-based methodologies and IRS-compliant documentation over low-cost providers.
- Liability Management: Understand that recommending a study makes your firm liable for its accuracy; conduct internal reviews.
- Client Education: Clearly distinguish cost segregation from property appraisals to manage client expectations.
- Regulatory Awareness: Stay updated on bonus depreciation rules, such as the 100% allowance for property acquired after January 19, 2025.
- Operational Efficiency: Use vendors with automated intake and reporting tools to minimize administrative burden.
- Value Proposition: Focus on the ROI of accelerated depreciation rather than the cost of the study itself.
- Audit Support: Ensure your white label partner provides robust audit support to protect your firm's reputation.
Frequently Asked Questions
What is the primary risk of using a low-cost white label cost segregation provider?
The primary risk is the lack of engineering rigor, which can lead to reports that fail to withstand IRS scrutiny. This can result in disallowed deductions and potential liability for the CPA firm.
How does cost segregation differ from a property appraisal?
Cost segregation focuses on reclassifying assets for tax depreciation purposes based on IRS guidelines, while a property appraisal determines the fair market value of the real estate for sale or financing.
Can cost segregation studies be applied to short-term rentals?
Yes, cost segregation is particularly powerful for short-term rentals. If the average stay is 7 days or less, the activity may not be treated as a rental activity, allowing depreciation deductions to offset non-rental income.
What is the typical turnaround time for a residential cost segregation study?
Standard residential reports often target a 2-business-day delivery after complete intake, though this can vary based on the complexity of the property and the vendor's capacity.
Do I need an on-site inspection for every cost segregation study?
Not necessarily. Many vendors use detailed photo analysis and public records to conduct property-specific studies without a physical visit, provided sufficient data is available.
How does bonus depreciation impact cost segregation?
Bonus depreciation allows for 100% first-year deduction of reclassified assets for property acquired after specific dates, such as January 19, 2025, significantly accelerating tax benefits.
What documentation should a white label partner provide?
A comprehensive report should include schedules, methodologies, an itemized CSV of assets, and a methodology file citing all relevant IRS regulations.
Start Your White Label Partnership
Implementing a white label cost segregation service is a strategic move that can elevate your CPA firm's value proposition. By avoiding common pitfalls in vendor selection, integration, and compliance, you can deliver exceptional results to your clients while protecting your firm's interests. If you are ready to expand your service offerings with a reliable, audit-ready partner, explore our partner program to learn how we can support your growth.