Common Mistakes When Reselling Cost Segregation White-Label Reports
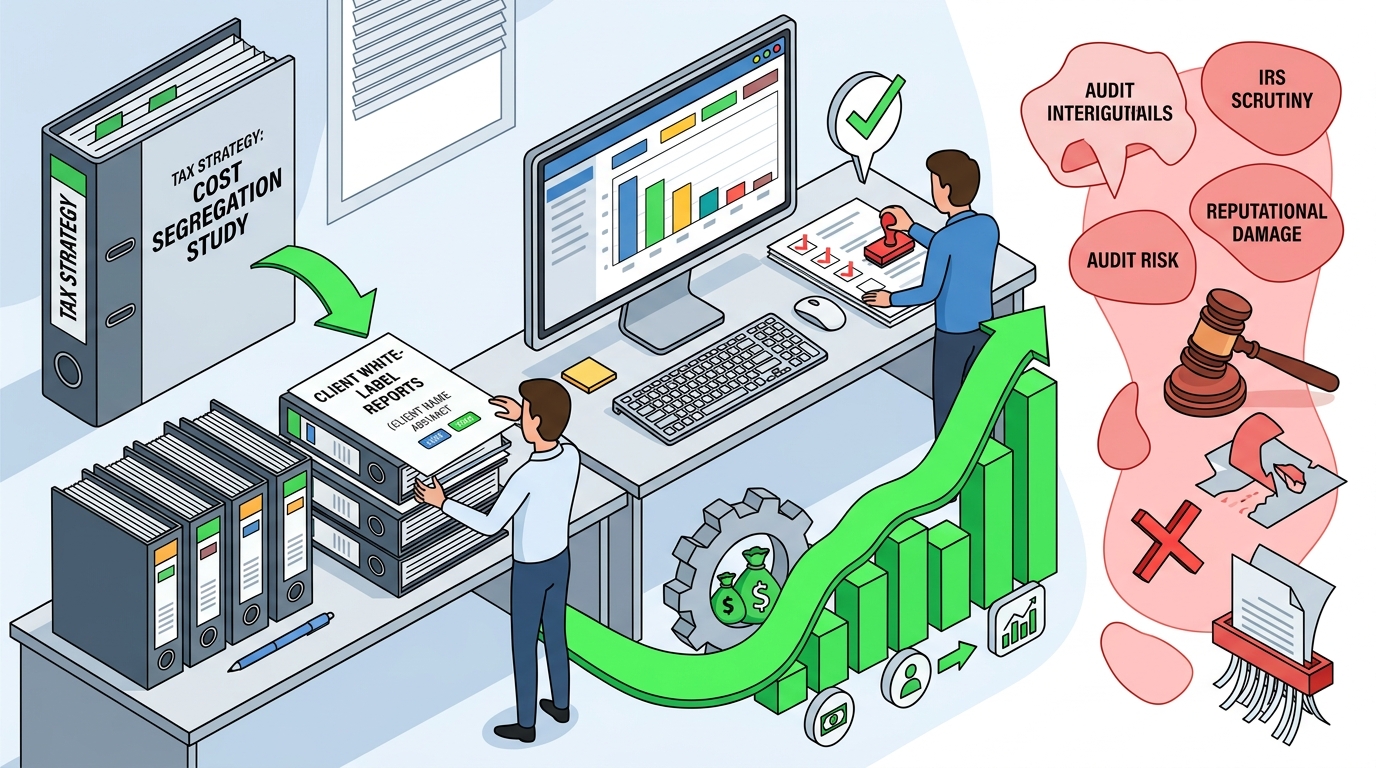
Cost segregation is a powerful tax strategy that allows rental property owners to accelerate depreciation deductions. For accounting firms and tax advisors, offering white-label cost segregation reports is a high-value service that can significantly increase client retention and revenue. However, the margin for error is slim. A single compliance mistake can lead to IRS scrutiny, client dissatisfaction, and reputational damage. According to the IRS Cost Segregation Audit Techniques Guide, the agency closely examines the methodology and documentation behind these studies. This article outlines the critical mistakes advisors make when reselling these reports and how to avoid them. (About RentalWriteOff Cost Segregation)
Methodology and Compliance Errors
One of the most frequent mistakes is relying on generic, non-property-specific reports. Cost segregation is not a one-size-fits-all solution. Each property has unique components that must be identified and classified according to IRS guidelines. Using a template that does not reflect the actual property details can lead to incorrect asset classifications and disallowed deductions. (Cost Segregation FAQ for)
Another common error is misclassifying assets into the wrong depreciation buckets. The IRS recognizes specific asset classes, such as 5-year, 7-year, and 15-year property, which depreciate faster than the standard 27.5-year building structure. Misclassifying a component, such as labeling landscaping as a 5-year asset instead of 15-year, can trigger an audit. It is crucial to ensure that the white-label report accurately reflects the property's physical characteristics and the applicable tax code. (RentalWriteOff Cost Segregation Studies)
Additionally, some advisors fail to update their knowledge of changing tax laws. For instance, the Tax Cuts and Jobs Act introduced significant changes to bonus depreciation, which impacts how and when deductions can be taken. Advisors must stay current with these changes to provide accurate advice to their clients. (RentalWriteOff Cost Segregation Studies)
Data Accuracy and Property Specifics
Accuracy in property data is paramount. Many advisors rely on incomplete or outdated information when ordering white-label reports. This can include incorrect square footage, year built, or lot size. These errors can skew the cost segregation analysis and result in inaccurate deductions. To avoid this, advisors should verify all property data with public records or direct client input before ordering a report.
Furthermore, failing to account for recent renovations or improvements is a significant oversight. Cost segregation studies should include all eligible components, including those added after the initial purchase. If a property has undergone significant upgrades, the study must reflect these changes to capture all potential deductions. Ignoring these additions can lead to missed opportunities for tax savings.
Another mistake is not distinguishing between personal property and real property. Only personal property and certain building components qualify for accelerated depreciation. Misidentifying real property as personal property can lead to compliance issues. Advisors must ensure that the white-label report clearly distinguishes between these categories.
Documentation and Audit Support
Comprehensive documentation is essential for defending a cost segregation study in the event of an IRS audit. Many advisors overlook the importance of detailed supporting documents, such as photos, invoices, and methodology files. Without these, the study may be deemed insufficient, leading to disallowed deductions and penalties.
Another common mistake is failing to provide adequate audit support to clients. Clients need to know that their advisor has their back if the IRS questions their deductions. Advisors should ensure that their white-label vendor offers robust audit support services. This includes having a team available to answer questions and provide additional documentation if needed.
Additionally, some advisors do not properly file Form 3115 for eligible look-back studies. This form is crucial for changing the method of accounting and claiming prior year deductions. Failing to file this form can result in lost tax benefits. Advisors must ensure that the white-label report includes guidance on filing Form 3115 when applicable.
Client Communication and Expectations
Clear communication with clients is vital to managing expectations. Many advisors fail to explain the benefits and limitations of cost segregation clearly. Clients may have unrealistic expectations about the amount of tax savings they will receive. It is important to provide a realistic estimate based on the property's specifics and current tax laws.
Another mistake is not educating clients on the long-term benefits of cost segregation. While the immediate tax savings are significant, the long-term impact on cash flow and investment returns is often overlooked. Advisors should highlight these benefits to help clients make informed decisions.
Furthermore, some advisors do not clearly communicate the timeline for receiving the report. Delays in receiving the report can impact the client's tax filing deadline. Advisors should set clear expectations regarding the turnaround time and ensure that the white-label vendor can meet these deadlines.
Vendor Selection and Quality Control
Choosing the right white-label vendor is critical to the success of your cost segregation service. Many advisors make the mistake of selecting a vendor based solely on price. While cost is important, it should not be the only factor. Quality, compliance, and support are equally important.
Another common mistake is not performing due diligence on the vendor's methodology. Advisors should ensure that the vendor's methodology aligns with IRS guidelines and industry best practices. This includes reviewing the vendor's quality control processes and ensuring that they have a team of qualified professionals reviewing each report.
Additionally, some advisors do not establish a clear feedback loop with their vendor. Regular communication with the vendor can help identify and resolve any issues quickly. Advisors should provide feedback on the reports they receive and work with the vendor to improve the service over time.
Key Takeaways
- Compliance is Key: Always ensure that the white-label report aligns with the IRS Cost Segregation Audit Techniques Guide to avoid scrutiny.
- Property-Specific Analysis: Generic reports are insufficient; each study must be tailored to the specific property's components and characteristics.
- Accurate Data: Verify all property data, including square footage and year built, to ensure accurate deductions.
- Comprehensive Documentation: Provide clients with detailed supporting documents, including photos and methodology files, to defend against audits.
- Audit Support: Choose a vendor that offers robust audit support to protect your clients and your firm's reputation.
- Clear Communication: Set realistic expectations with clients regarding tax savings, timelines, and the cost segregation process.
- Vendor Due Diligence: Select a vendor based on quality, compliance, and support, not just price.
Frequently Asked Questions
What is cost segregation?
Cost segregation is a tax strategy that involves reclassifying certain components of a building from real property to personal property, allowing for accelerated depreciation deductions.
Why is a property-specific report important?
A property-specific report ensures that all eligible components are identified and classified correctly, maximizing deductions and ensuring compliance with IRS guidelines.
Can cost segregation studies be used for short-term rentals?
Yes, cost segregation studies can be particularly beneficial for short-term rentals, as they may allow for the offset of non-rental income if material participation rules are met.
What is Form 3115?
Form 3115 is used to request a change in accounting method, which is often necessary for claiming prior year cost segregation deductions.
How long does it take to receive a cost segregation report?
Turnaround times vary by vendor, but many offer expedited services, with some providing reports within two business days after complete intake.
What should I look for in a white-label vendor?
Look for a vendor that offers IRS-compliant methodology, property-specific analysis, comprehensive documentation, and robust audit support.
Can I offer cost segregation services without being a CPA?
While you do not need to be a CPA to offer cost segregation services, it is important to work with qualified professionals and ensure that your advice is compliant with tax laws.
Start Your White-Label Partnership
Avoiding these common mistakes can help you provide high-quality cost segregation services to your clients. If you are looking for a reliable white-label partner, consider partnering with RentalWriteOff. Our engineering-based, expert-reviewed reports are designed to meet the highest standards of compliance and accuracy. Book a free consultation today to learn more about how we can help you grow your practice.